

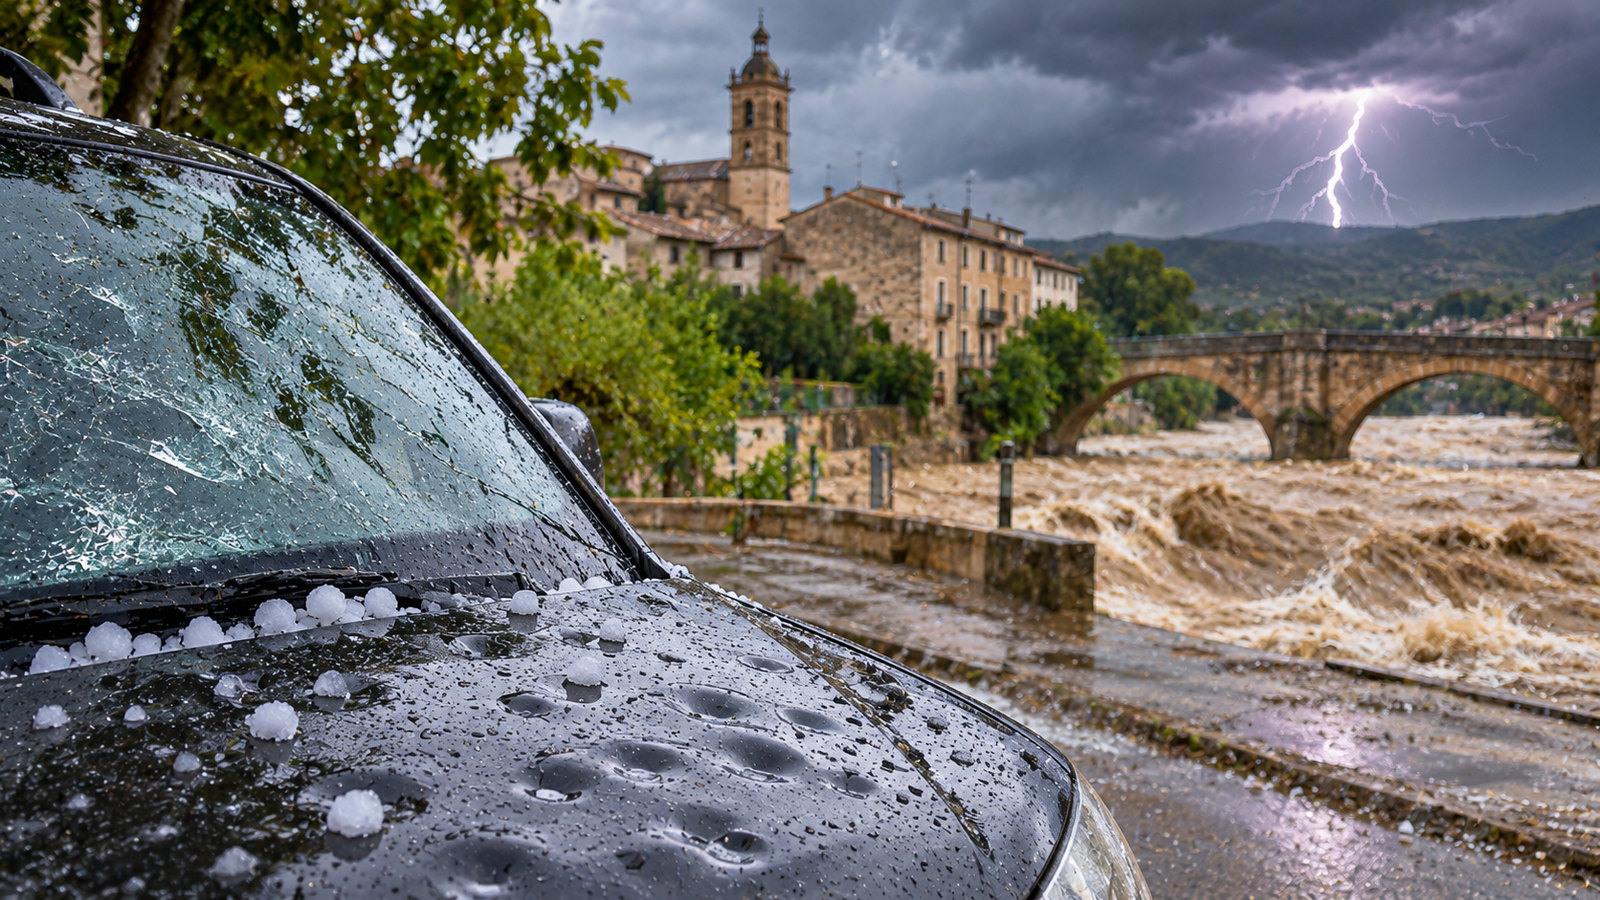
Late-summer storms have become an almost regular occurrence in Zaragoza and much of the region. After each episode, the same question arises: who pays for the damage? The answer depends on the event that caused it, and the distinction is not always intuitive.
Insurer or Consorcio
The basic division is summarized by the Zaragoza Insurance Brokers Association: the Consorcio de Compensación de Seguros covers all flood-related damage, while private insurers cover direct damage from rain and hail.
Hail is the case that causes the most surprise. Even when hailstones are the size of golf balls, hail is not included on the statutory list of extraordinary risks, regardless of its intensity. As a result, such damage is covered by the private insurer, provided the policy includes it. For vehicles, hail damage to bodywork and windows is compensated only if the policy includes glass coverage or own-damage coverage; under a basic third-party policy, the owner must pay for repairs.
Rain is handled similarly: the Consorcio never covers it, regardless of its intensity, although it does cover flooding. Many home insurance policies also set a threshold: according to Ucaragón, insurers typically cover damage once rainfall exceeds 40 liters per square meter. This can be verified through AEMET records.
By contrast, if flooding sweeps away a vehicle or inundates a business premises, the Consorcio comes into play. Importantly, no separate policy is required: every auto, home, or commercial insurance policy includes a surcharge that finances this coverage. The requirement is that the policy be in force and the premium paid.
Deadlines not to miss
After a loss, it must be reported to the insurer within seven days. Policyholders should keep invoices and take photographs before cleaning up or throwing anything away. Those without insurance will receive no compensation from either insurers or the Consorcio, and may only qualify for public assistance if the area is officially declared severely affected by a civil protection emergency.
For businesses, there is an additional consideration: the Consorcio applies a 7% deductible to losses, which can represent a significant amount for a warehouse or store.
“After a storm, half the inquiries we receive come from clients who did not know whether their policy covered hail or only flooding,” say representatives of the Zaragoza-based insurance brokerage Duet Seguros. Their advice is to review coverage before storm season, not afterward, and to check both the rainfall threshold and the deductible under home or business insurance.