

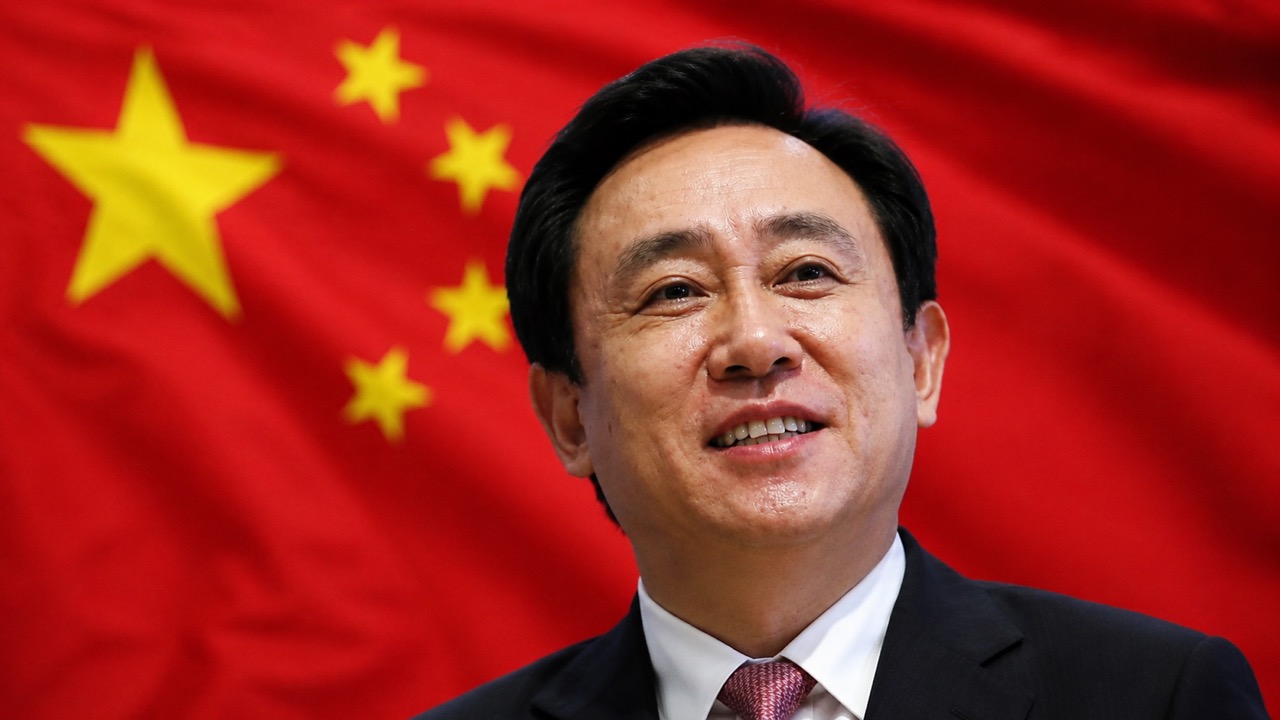
In September 2021, as Evergrande began to stagger under a mountain of debt, Xu Jiayin still publicly believed he could save the company. In a letter to his employees, he assured them that with effort and hard work, the group would overcome what he referred to as its darkest moment. At that time, the company was burdened with around $300 billion in liabilities, and markets were trying to determine just how far the repercussions of its potential collapse could extend.
Five years later, that story has a very different ending. Evergrande has entered bankruptcy, a Hong Kong court has ordered its liquidation, its shares have vanished from the stock market, and Xu Jiayin has been sentenced to life in prison by the Chinese justice system. The businessman, who once embodied the wealth-making opportunities arising from China’s economic transformation, has ultimately lost all his assets and his political rights for life.
His journey tells more than just the tale of a fallen entrepreneur. Evergrande grew at the same time that millions of Chinese moved to cities, housing became one of the primary destinations for household savings, and the real estate sector acquired immense weight in the economy. Xu was able to leverage that trend, but he built his expansion on a mounting debt load that ultimately rendered the group unsustainable when Beijing decided to rein in the financial excesses of the sector.
From Rural Poverty to One of China’s Richest Men
Xu Jiayin was born in 1958 in Henan Province, into a poor rural family. He lost his mother while still a child and was largely raised by his grandmother. After studying metallurgy, he worked for years in the steel industry until the 1990s, when he entered the real estate business, just as urbanization and economic reforms were creating a housing market of previously unknown dimensions in China.
In 1996, he founded in Guangzhou the company that would eventually become Evergrande. His formula was based on acquiring land, quickly building, selling properties, and using the revenues and new financing to start more projects. The group grew as real estate prices, housing demand, and credit availability escalated, ultimately becoming one of the major players in China’s property expansion.
A Model That Needed to Keep Growing
The problem with Evergrande was not merely that it had debt. The growth of large Chinese property developers had relied for years on a model that required a continuous flow of financing, home sales, and new projects. In China, it is common for buyers to pay for their homes before they are completed, and these pre-sales provided developers with resources to continue building and expanding. As sales increased, credit remained available, and real estate prices maintained their upward trajectory, the mechanism allowed for rapid growth.
Evergrande took this strategy to an extraordinary scale. The company borrowed money from banks and other creditors, issued debt, and secured financing through various instruments while continuing to buy land and develop projects across the country. Scale became an advantage as the market grew, but it also increased the company’s exposure to any changes in financing conditions.
That change arrived when the Chinese government decided to rein in the debt levels of developers. Beijing believed that the growth of credit and housing prices was generating risks for economic stability and, in 2020, introduced the so-called «three red lines,» a series of financial criteria aimed at limiting the ability of the most indebted real estate companies to continue accumulating liabilities. Evergrande was particularly exposed.
During 2021, its difficulties in obtaining liquidity began to surface. The company attempted to sell assets and raise funds as doubts about its ability to meet financial obligations increased. By the end of that year, when it finally ceased to meet some of its international debt obligations, it accumulated over $300 billion in liabilities, placing it among the most indebted property developers in the world.
What Came After the Collapse
The verdict issued in August 2026 adds another dimension to this story, as Evergrande’s problems stemmed not only from an excessively indebted business strategy. The Shenzhen court found that between 2016 and 2021, Evergrande and Xu Jiayin continuously falsified financial information, inflating assets and concealing liabilities. Xu was also convicted of crimes related to illegal fundraising, embezzlement, fraud, and bribery.
Authorities had previously accused the group’s main real estate subsidiary of inflating its revenues in 2019 and 2020. The ruling now imposes a life sentence on Xu, confiscation of all his assets, and loss of his political rights. Evergrande Group has been fined 8.82 billion yuan, and Evergrande Real Estate another 7 billion, while dozens of individuals have been convicted within proceedings related to the group.
Evergrande Fell, but the Real Estate Crisis Continued
The collapse of Evergrande was not an isolated incident. The Chinese real estate market entered a long adjustment process that continues five years later. Housing sales remain well below the peaks reached in 2021, prices have undergone a significant correction, and financing for developers has decreased. Beijing has adopted various measures to stabilize the market and, particularly, to ensure that the homes millions of citizens had purchased before construction are completed.
The issue has implications that extend beyond the property development companies. For years, housing has represented a very significant portion of household wealth in China, while construction and land sales played a crucial role in economic activity and the finances of local governments. A prolonged decline in the real estate market could therefore affect family confidence, their consumption and saving decisions, and the financial capacity of local administrations.
The International Monetary Fund continues to view a larger-than-expected contraction in the real estate sector as one of the main internal risks to the Chinese economy. At the same time, the country is trying to find new sources of growth and has gained international ground in industries such as electric vehicles, batteries, artificial intelligence, and robotics while seeking to gradually reduce its dependence on the real estate investment that characterized much of the previous decades.