

Questions about how long the extraordinary level of investment in artificial intelligence can be sustained have been accompanying major tech companies for months. Nvidia’s latest results provide, at least for now, a resounding answer: the demand for computing capacity continues to grow at a pace rarely seen in any other large industry.
Nvidia closed the second quarter of its fiscal year 2027 with revenues of $96.221 billion, a 106% increase from the same period last year. Net income reached $59.688 billion, compared to $26.422 billion a year earlier, according to the results published by the company. In just twelve months, the manufacturer has more than doubled both its revenue and its profits.
The explanation lies primarily in data centers. This division generated $89 billion during the quarter, a 117% increase from a year ago, accounting for approximately 92.5% of Nvidia’s total revenue. The prominence this business has gained shows how the company, which for years was primarily known for its graphics cards, has transformed into one of the leading providers of the infrastructure on which artificial intelligence is being built.
And Nvidia does not expect an immediate slowdown. Its forecast for the third quarter places revenue around $108 billion, with a margin of plus or minus 2%. The company also anticipates strong growth during the next fiscal year, while continuing to expand the capacity needed to meet the demand from major cloud service providers, businesses, and artificial intelligence projects developed by various countries.
Investment in AI Continues to Fuel Demand
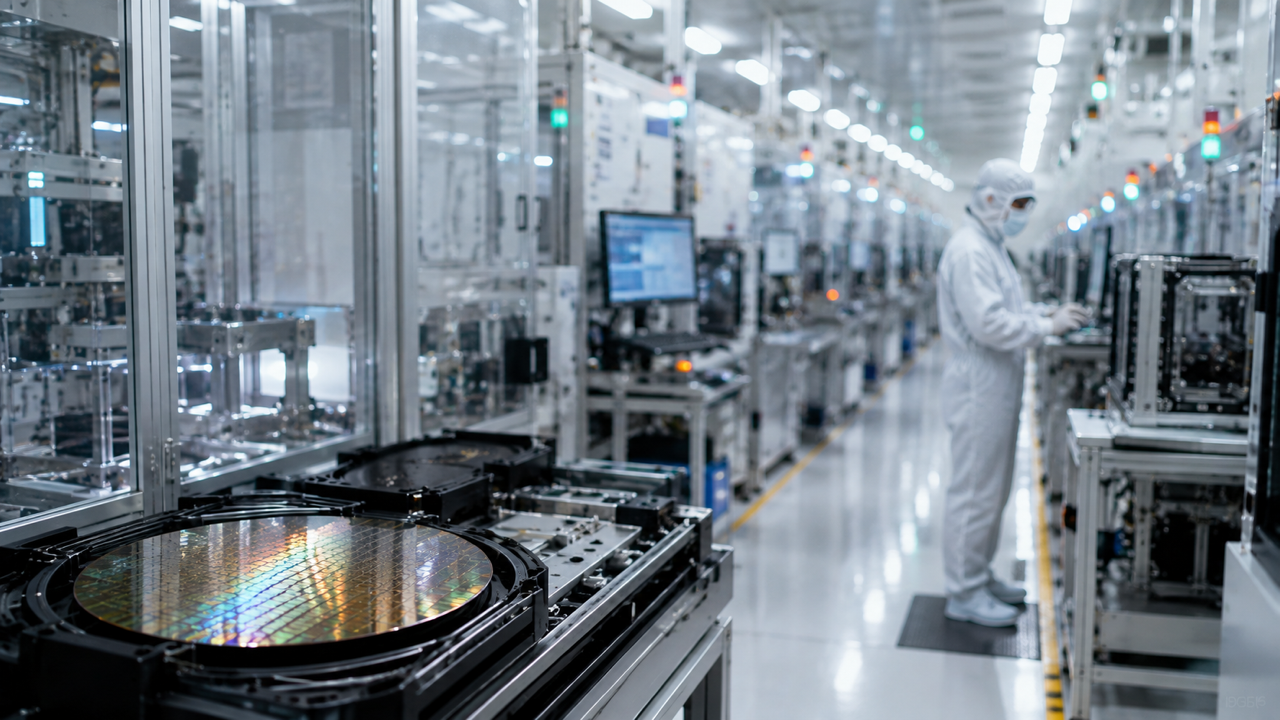
Nvidia’s growth is closely linked to the enormous amounts of capital that major tech companies are allocating to data centers. Training and operating increasingly complex models requires thousands of processors working together, as well as memory, high-speed networks, cooling systems, electricity, and large facilities capable of housing all that infrastructure.
Nvidia occupies an exceptional position within that chain because its GPUs have become one of the fundamental components of large artificial intelligence systems. The company’s advantage lies not solely in manufacturing processors. For years, it has built an ecosystem of software, networks, and tools that facilitate developers and companies working on its architecture, making it difficult for its customers to switch providers quickly.
The next generation of products must reinforce that position. The Vera Rubin platform is entering production, and Nvidia expects it to contribute to sustaining growth over the coming quarters. The company is trying to accelerate the pace at which it introduces new architectures while its competitors and some of its own major clients develop alternatives.
Amazon, Google, and Microsoft, among other tech groups, are working with proprietary processors designed for specific artificial intelligence workloads. AMD also competes directly with Nvidia in accelerators for data centers. The size of the market currently allows different solutions to coexist, although Nvidia’s leadership remains one of the elements explaining its margins and profits.
The company is also trying to ensure that the availability of financing does not become a limit to expanding infrastructures. In its results, it highlighted agreements with major financial and investment groups such as Apollo, BlackRock, Blackstone, Brookfield, Goldman Sachs, and KKR to develop independent platforms capable of mobilizing, over time and subject to definitive agreements, more than $500 billion in third-party capital for artificial intelligence infrastructure.
This figure helps to put into perspective the scale the phenomenon is acquiring. The development of AI no longer depends solely on the technological decisions of a few Silicon Valley companies. It is mobilizing investment funds, banks, energy companies, data center operators, and governments, all of which are necessary to finance and build the facilities required for increased computing capacity.
China Remains an Unknown
The extraordinary growth does not eliminate risks. One of the main ones continues to be China, a market that Nvidia cannot access normally due to the restrictions imposed by the United States on the export of certain advanced semiconductors.
The company itself has indicated that its forecast for the next quarter does not include revenues from sales to data center clients in China. The evolution of relations between Washington and Beijing may determine whether Nvidia regains part of that market or if Chinese manufacturers gradually reduce their dependence on U.S. technology.
There are also tensions in the supply chain. The simultaneous growth of data centers is increasing the demand for memory and other components needed to manufacture artificial intelligence systems. The rising costs of some of these elements may exert pressure on margins even in a moment of exceptional sales growth.
But the biggest unknown is likely outside of Nvidia. Major tech companies are allocating increasing amounts to build AI infrastructure, and the market will ultimately demand that these investments generate sufficient returns. As long as this spending continues to grow, Nvidia will keep finding buyers for its processors. The question will be what happens when investors begin to compare the capital invested with the revenues and profits generated by artificial intelligence more rigorously.
The results published this week indicate that this moment has not yet halted the cycle. Nvidia has just surpassed $96 billion in quarterly revenue and expects to break the $100 billion barrier in the next quarter. At the same time, new data centers continue to be built, and the financial industry is beginning to mobilize capital on a scale that, just a few years ago, would have been hard to imagine for an emerging technology.
Nvidia’s growth does not prove that all investments in artificial intelligence will be profitable, nor does it resolve the debate over the valuations of companies linked to the sector. It does confirm something more concrete: the companies building the global AI infrastructure have not yet taken their foot off the accelerator. And as long as that race continues, Nvidia will remain one of the most profitable players in the chain.