

Spain is becoming an important part of Chinese automakers’ industrial expansion in Europe. What began with the arrival of new brands and imported vehicles is entering a different phase: producing within the continent, leveraging existing factories and forming partnerships with European groups. In this new landscape, Zaragoza already holds a significant position.
The latest signal has come from BYD. Alfredo Altavilla, the Chinese manufacturer’s special adviser for Europe, told Reuters that the company is looking for existing production facilities it can acquire and quickly adapt. Spain and France are among the most viable options, according to Altavilla.
BYD has not yet selected the new location and, therefore, no Spanish factory has been awarded. Its strategy nevertheless points to a broader shift. Chinese manufacturers are no longer viewing Europe solely as an export destination and are beginning to build their own industrial presence, either independently or jointly with European companies.
Future EU local-content requirements are accelerating the process. For Chinese manufacturers, producing within the European Union also reduces exposure to trade barriers affecting electric vehicles imported from China.
BYD has already started European production in Hungary and plans to select a second location before the end of the year. In the long term, the company estimates it will need three assembly plants and a battery factory to serve the European market.
Figueruelas is already part of that landscape
In Aragon, the process has specific names: Stellantis and Leapmotor. The European group and the Chinese manufacturer announced in May their intention to expand the partnership they have maintained since Stellantis acquired a stake in Leapmotor and the two companies developed Leapmotor International.
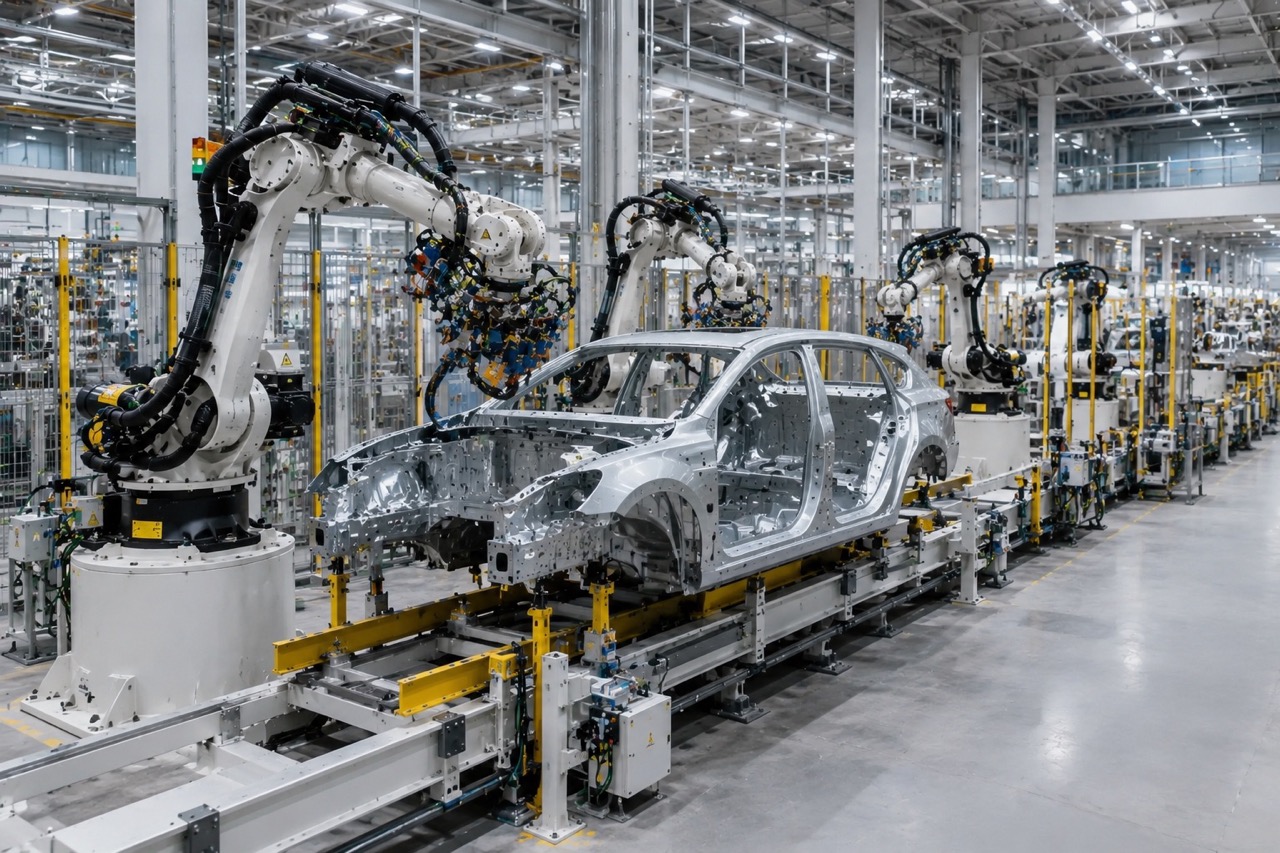
One of the main projects is located in Figueruelas. The two companies are considering producing the Leapmotor B10 there, a C-segment electric SUV, with manufacturing potentially beginning in 2026.
The plan goes further. Stellantis and Leapmotor are also assessing the addition of a new line to manufacture a fully electric Opel C-SUV in Zaragoza, designed and developed in Rüsselsheim. Production could begin from 2028.
The project’s industrial distinction lies in how capabilities would be divided. The Opel vehicle would be European in its design and manufacturing, but could incorporate components from the Leapmotor International ecosystem. Stellantis sees such cooperation as a way to reduce costs and speed the launch of new electric models.
Figueruelas, therefore, would not merely be a European factory used to assemble a Chinese car. The approach being considered by the companies combines technology, components, procurement and industrial capacity from both sides.
For a plant that has been producing cars for more than four decades, the partnership represents an adaptation to a market very different from the one that saw the Opel Corsa launched in 1982.
From Figueruelas to Mallén
China’s presence in Aragon already has another, less visible component. In June, Leapmotor International announced the opening of a battery workshop in Mallén, near Zaragoza.
The facility is intended for module assembly and other processes related to the batteries required for electric-vehicle production. The company itself presented the project as a move from an initially commercial partnership toward an effective industrial presence in the region.
The combination of Figueruelas and Mallén is significant because it shows how the arrival of a manufacturer can begin to spread across different parts of the value chain.
Electrification has reshaped that chain. Batteries, electronics, software and new components have gained importance, while some traditional parts used in internal-combustion vehicles have lost ground. For regions with an established automotive industry, retaining factories also requires incorporating activities linked to electric vehicles.
Barcelona offers another model
Zaragoza is not an isolated case. In Barcelona, the alliance between Ebro and Chinese manufacturer Chery has helped restore industrial activity at the former Nissan facilities in the Zona Franca.
The two companies have already invested more than €150 million in transforming the factory. This summer, a new line began operating with additional capacity to produce 250 vehicles a day, which, according to the company, triples previous capacity.
The model differs from that of Stellantis and Leapmotor, but it reflects the same transformation. A Chinese company gains European manufacturing capacity without having to build a major factory from scratch, while Spain retains industrial activity at facilities that already have workers, suppliers, logistics and accumulated expertise.
That final factor is beginning to take on particular importance.
Building a factory takes years and requires substantial investment. Moving into an existing facility shortens timelines and makes use of an industrial ecosystem that is already operating. Altavilla has acknowledged that BYD is considering precisely this route to accelerate its European expansion.
Spain has several characteristics that place it on that radar: a long automotive tradition, plants with industrial capacity, an extensive supplier network and a significant position in European vehicle manufacturing.
From competitors to industrial partners
The entry of Chinese manufacturers is also creating a more complex relationship with Europe’s auto industry. They are competitors in the market, but are also beginning to become industrial partners.
Stellantis holds a stake in Leapmotor and uses the alliance to develop its electric-vehicle offering. Ebro manufactures alongside Chery in Barcelona. Other European manufacturers are exploring collaborative arrangements to share technology, platforms, components or production capacity.
The trend comes at a delicate time for Europe’s auto industry. Traditional manufacturers face the cost of electrification, growing competition and the need to offer electric vehicles at more affordable prices. Chinese brands, for their part, need to manufacture within Europe to consolidate their presence and reduce their exposure to tariffs and future local-content rules.
Their interests are not identical, but in certain projects they are beginning to converge.
The question is how value will be distributed within these partnerships. Manufacturing vehicles in Spain preserves industrial activity and may generate new investment, but it will be equally important to see where engineering, technological development, suppliers, batteries and higher-value components are located.
This debate will be especially relevant for regions such as Aragon, where the automotive industry does not end at the gates of Figueruelas. Around the plant is an auxiliary industry built over decades and directly exposed to the sector’s technological changes.
What happens with Leapmotor could therefore serve as an early indicator of the extent to which the new relationship with Chinese manufacturers also translates into opportunities for suppliers, engineering, logistics and specialized employment in the region.
The arrival of the battery workshop in Mallén points in that direction, although