

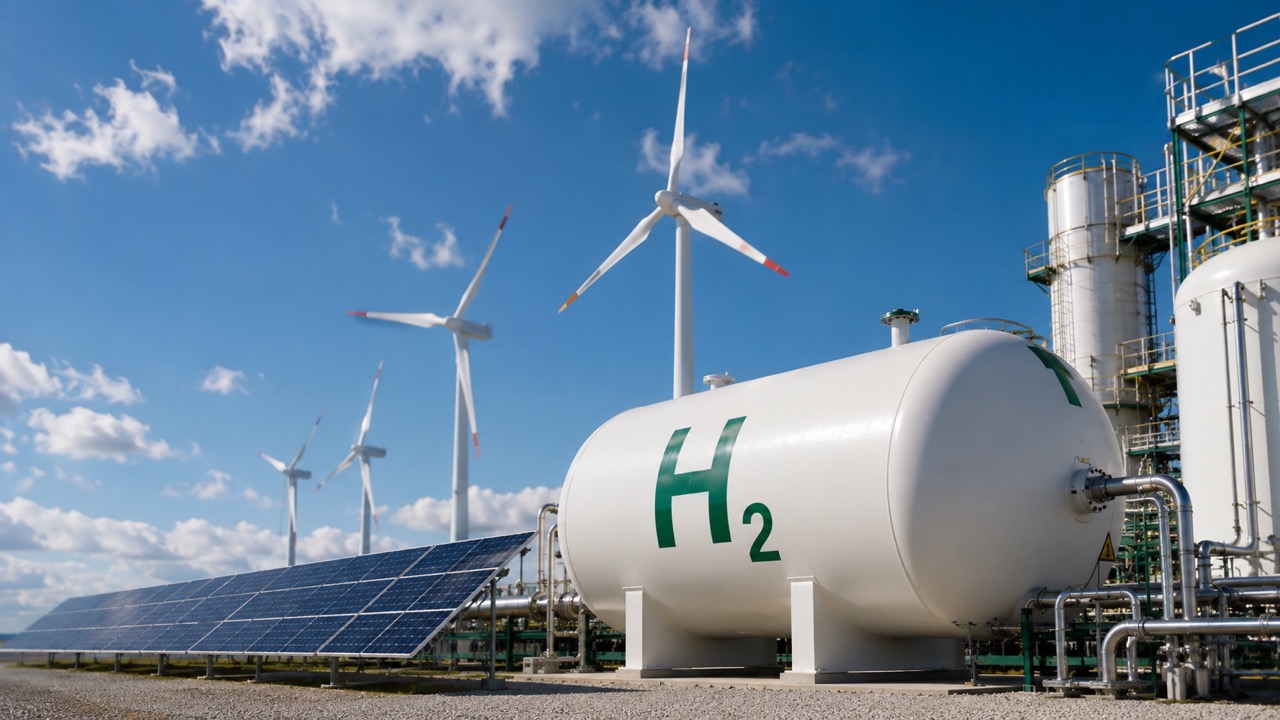
Spain has been consistently ranked among the European countries with the greatest potential for developing green hydrogen. The abundance of solar and wind resources, an industry that needs to reduce its emissions, and the opportunity to produce renewable electricity at competitive costs have fueled numerous projects. The challenge, however, has always been converting that energy potential into industrial facilities capable of large-scale production.
Some of these projects are now beginning to enter a different phase. Moeve has made the final investment decision for Onuba, the first phase of its Andalusian Green Hydrogen Valley in Palos de la Frontera (Huelva), while Repsol is advancing large-capacity electrolyzers linked to its industrial complexes in Cartagena and Petronor, in Bilbao. Together, these investments demonstrate how renewable hydrogen is starting to be integrated into the transformation of some of Spain’s key energy and industrial hubs.
The Moeve project is one of the most significant in terms of scale. The company announced in March an investment exceeding €1 billion to develop Onuba, which will initially have 300 MW of electrolysis capacity and plans to add another 105 MW. The installation is part of a broader plan that the company is developing in Andalusia, with the final dimensions depending on the execution of the successive planned phases.
The so-called Andalusian Green Hydrogen Valley proposes two major production centers in Huelva and San Roque, in Cádiz. If the complete project reaches the announced scale, it could achieve 2 GW of electrolysis capacity and produce up to 300,000 tons of renewable hydrogen annually. However, these figures correspond to the overall projected development and not to the installation currently committed in Huelva.
From producing renewable electricity to using it in industry
The economic interest in green hydrogen largely lies in its ability to connect renewable generation with industrial activities that are difficult to electrify directly. Hydrogen produced through electrolysis using renewable electricity can progressively replace hydrogen obtained from fossil fuels that are already consumed by refineries and other industries.
It can also be used as a raw material to produce renewable fuels and derivatives intended for sectors where electrification poses greater challenges. This is why a significant portion of Spanish projects is being developed around existing industrial complexes, where there is already energy consumption, infrastructure, and potential demand for the new production.
Repsol is precisely following this strategy. The company has approved two electrolyzers of 100 MW each linked to its Cartagena and Petronor complexes. The Cartagena project represents an investment exceeding €300 million, while the Petronor project reaches €292 million, according to figures communicated by the company.
Additionally, both projects benefit from public support within European programs aimed at promoting technologies necessary for industrial decarbonization. Repsol has indicated that both electrolyzers have collectively received €315 million in funding associated with their designation as projects of European common interest.
This backing is significant because renewable hydrogen continues to face a cost disparity compared to conventional alternatives. Public subsidies, European support mechanisms, and the gradual creation of industrial demand are part of efforts to narrow that gap during the early stages of market development.
A European industrial race
Spain is not alone in this strategy. The European Union considers renewable hydrogen one of the essential technologies for reducing emissions from certain industrial processes and decreasing dependence on imported fossil fuels. Brussels has developed various financial instruments over the past few years to accelerate investments and foster the emergence of a European market.
In March 2026, the European Commission approved a Spanish aid scheme worth €440 million aimed at supporting the production of renewable hydrogen. These resources are complemented by other national and community programs designed to facilitate the construction of electrolyzers and stimulate demand.
However, the existence of financing does not guarantee the development of a competitive industry on its own. Hydrogen requires significant amounts of renewable electricity, infrastructure for storage and transportation, and, above all, buyers willing to commit to consuming it for sufficiently long periods to justify investments.
This last point has become one of the main challenges for numerous European projects. In the initial years of the hydrogen race, very high capacities were announced that subsequently faced difficulties in reaching definitive investment decisions. Therefore, the transition from forecasts to execution is as crucial as the initially announced size.
The opportunity to build industry around energy
The Spanish advantage may extend beyond having sun, wind, and land to produce electricity. The economic question is how much of the added value associated with that energy can remain in the country.
If renewable hydrogen is used to decarbonize refineries, produce next-generation fuels, or supply certain industries, energy availability can become a location factor for new investments. Furthermore, significant projects create opportunities for engineering firms, electrolyzer and component manufacturers, construction, maintenance, storage, logistics, and specialized services.
This industrial effect will be one of the elements that determine the success of the Spanish strategy. Producing large quantities of renewable electricity and subsequently transforming it into hydrogen for export constitutes a very different scenario than using that energy advantage to attract or retain industrial activities within the territory.
The Moeve and Repsol projects will still need to demonstrate their economic viability and meet the planned timelines. Green hydrogen remains an emerging industry, with uncertainties surrounding future costs, the speed of demand growth, and the infrastructure necessary to connect producers and consumers.
What is starting to change is the nature of some projects. After several years dominated by targets, announcements, and capacity plans, certain Spanish initiatives are mobilizing investments and entering execution phases. The likelihood that Spain can turn its renewable strength into an industrial advantage will depend on how many of these projects successfully complete this journey and the economic activity they can generate around them.