

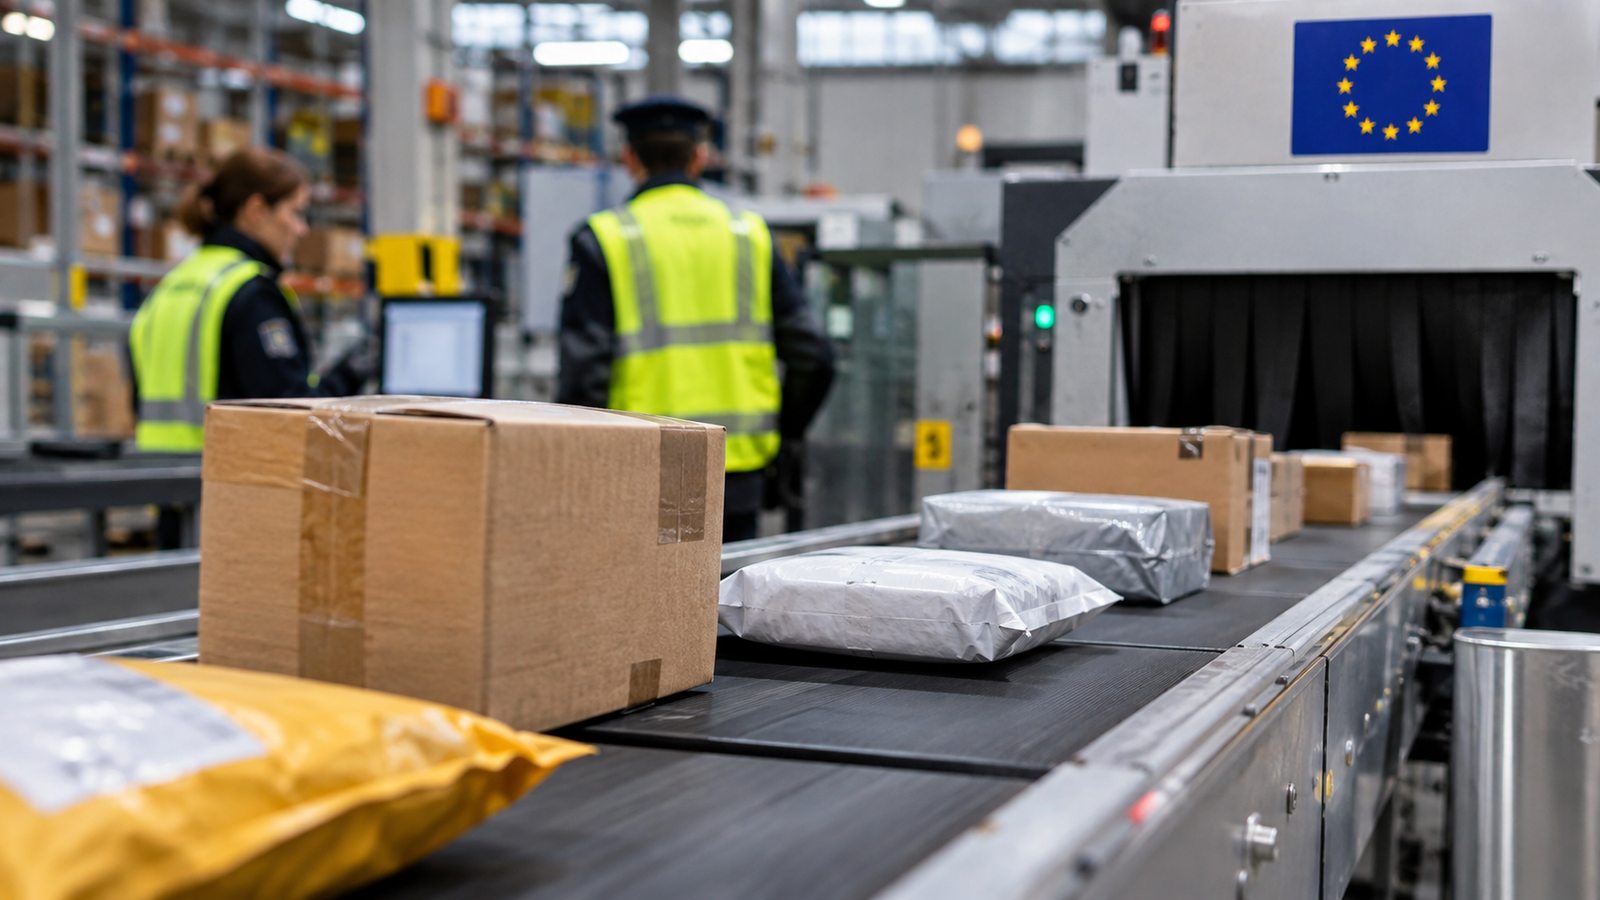
Online purchases shipped directly from countries outside the European Union have been subject to a new customs cost since November 1, 2026: a €2 processing fee for each product category. The charge is added to the taxes and duties already applicable to these transactions and also affects distance sales with shipments valued at more than €150.
The measure is intended to fund the checks and oversight carried out by customs authorities amid the growth of e-commerce. These include verifying goods data, assessing risks, and conducting documentary or physical inspections. For consumers and sellers, its impact depends on the composition of the order and on how payment of import charges has been arranged.
The first distinction is crucial: it is not €2 per package, nor necessarily for each physical unit. Spain’s Tax Agency explains that the amount is calculated by product category, linked to the line item in the customs declaration. As a result, combining several products in a single box does not guarantee that only €2 will be charged.
An example from Ireland’s tax administration helps illustrate the rule. A shipment containing a pen, a notebook, and a keychain includes three different items and incurs a €6 fee. By contrast, two identical pens treated as a single item for declaration purposes incur a €2 charge. Customs classification determines the calculation; simply counting the units in an order is not enough.
Two separate charges from July and November
The processing fee should be distinguished from the fixed €3 customs duty introduced on July 1, 2026, for online purchases shipped from outside the EU and valued at up to €150. That change removed the duty exemption that had benefited such small shipments, although they were already subject to VAT.
Since November, when a transaction falls under that regime, both charges apply: a €3 customs duty and a €2 fee for each declared category. An order with a single category therefore incurs €5 in those two charges, before any applicable VAT. With three categories, the total rises to €15.
For shipments valued above €150, customs duty is calculated according to the tariff applicable to the goods, rather than using the fixed €3 amount. The new processing fee also applies. It must also be distinguished from the handling charges a carrier may impose for filing the declaration: those reflect the carrier’s own service and are not subject to a price set by the European fee.
Who pays customs authorities
In Spain, the Tax Agency requires payment from the declarant appointed by the seller or platform to complete customs formalities. It does not claim the amount directly from the consumer unless the consumer files the paperwork in their own name.
This does not prevent the buyer from ultimately bearing the cost. The seller may include it in the amount charged at checkout; if it does not, the carrier may request payment before delivering the goods. Liability to customs authorities and passing the economic cost on to the customer are separate matters.
The shipment’s actual origin also matters. A store with a Spanish domain name or prices in euros may dispatch goods from a non-EU country. Conversely, a purchase of goods already in free circulation within the EU does not create a new import simply because it is delivered to the consumer from another member state.
For e-commerce businesses, the change requires a review of pricing, sales terms, and agreements with logistics providers. Starting in November, it also introduces product-identification requirements for declared goods, according to information published by Spain’s Tax Agency.
The proportional impact of a fixed charge is greater for low-cost orders. For a company selling directly from outside the EU, absorbing it reduces margins; passing it on changes the final price. Importers must distinguish these distance sales from their regular commercial operations: the new fee does not allow a uniform surcharge to be automatically applied to every import. The sales model, declaration, and products included remain decisive.